 Bufetico

If you own PepsiCo stock, or you’ve had your eye on it for the dividend, you probably think of it as the stock you never have to worry about. People buy chips and soda in good years and bad. James McPherson drove trucks for PepsiCo.
McPherson is 42. In September 2026 he hit 21 years at PepsiCo’s plant in Cheverly, Maryland, a town of about 6,000 just outside Washington. He started out making deliveries in Northern Virginia, then moved to driving tractor-trailers between warehouses. A shift was about 500 miles and around 12 hours. On the job he was robbed twice. He called the job a badge of honor, because not everybody could do it.
On September 14, the day after his anniversary, PepsiCo shut down the factory, the warehouse and the trucks that ran between warehouses, the work McPherson did. It laid off 143 people, The Washington Post reported on October 18. The plant had been there for more than 60 years, and it’s the town’s biggest employer and biggest taxpayer.
McPherson has two kids, 11 and 8. He has filled out more than 20 job applications, mostly to drive trucks again. He still wakes up around 1 a.m., the way he did for work, and he still carries his work badge in his wallet. He told the Post what went through his head that day: “I have to figure out what my life is now.”
PepsiCo said the decision “was not made lightly.” It also said its network has to keep changing with demand and technology. The workers keep their pay and benefits until November 13, and those who qualify get severance. PepsiCo’s sales and delivery teams are still at the site.
What PepsiCo told its shareholders in October
For a town of about 6,000, those 143 jobs were a lot. In PepsiCo’s numbers, you can barely see them. Its annual report shows $93.9 billion of snacks and drinks sold in 2025, about 2 percent more than in 2024.
On October 8, 2026, PepsiCo reported its third quarter. It lowered its forecast for how much its profit per share will grow in 2026, to 1 to 2 percent, leaving out currency swings. Before, it expected at least 4 percent. In the same release, it kept its plan to hand its shareholders $8.9 billion in 2026: $7.9 billion in dividends and $1.0 billion in stock buybacks.
The three questions I ask
When I look at a company, I always go in the same order. I start with whether it’s financially stable. For me that means it doesn’t owe much, it makes a good profit on the money it puts in, and it brings in cash. That’s what lets a company ride out a crisis. Next, I ask if it’s growing, even a little. Cheap or expensive, I ask last.
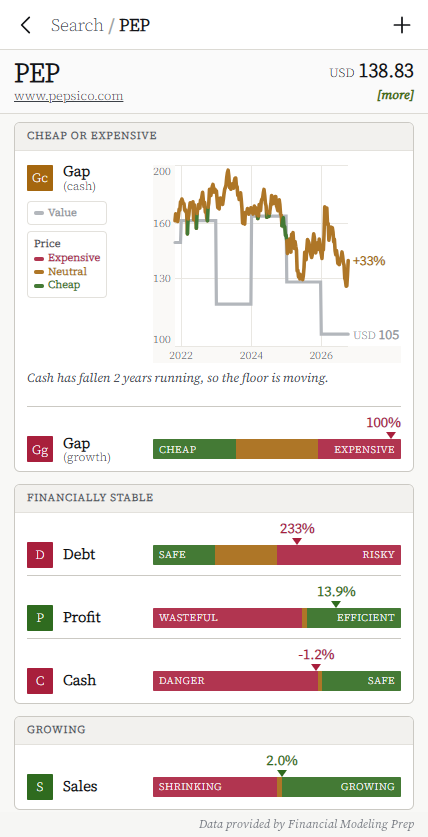
PepsiCo makes a good profit on its money, and its sales keep growing, slowly. In Bufetico, its profit and its sales come out green. Its debt and its cash come out red.
The debt is easy to see. Counting the part due within a year, PepsiCo’s long-term debt went from $41.2 billion at the end of 2024 to $46.4 billion at the end of 2025. That same year it spent $3.39 billion buying companies, poppi and Siete among them, and $1.0 billion buying back its own stock.
The cash takes a little more math. In 2025 its operations brought in $12.09 billion of cash. It spent $4.42 billion on plants and equipment, so it kept $7.67 billion. That year it paid $7.64 billion in dividends.
Then I look at the price. On October 22, 2026, PepsiCo closed at $138.83 a share. There are about 1.36 billion shares, so the whole company was priced at about $189 billion. That’s about 25 years of the cash it kept in 2025, for a business whose sales grew about 2 percent. In Bufetico the Gap (growth) is red. It puts the price next to how fast the company grows, and red there means expensive. The Gap (cash) is orange, which means the price sits above the cash too, just not as far.
Where this breaks
PepsiCo counts its free cash flow a bit higher than I do, because it adds the money it gets from selling property. By its count, the dividend took about 93 percent of that cash in 2025. That’s tight, but it isn’t all of it. PepsiCo has paid a dividend every quarter since 1965, and it expects at least 80 percent of its core profit to end up as free cash flow in 2026. That’s PepsiCo’s forecast, not mine.
Cheverly is also one plant, and nothing PepsiCo has filed ties it to the dividend.
McPherson’s 21st year and one line in the cash flow statement
You can only stretch your legs as far as your blanket goes. For PepsiCo, the blanket is the cash it keeps after paying for its plants and equipment, and the dividend has been right at the edge of it for three years.
In 2024 PepsiCo kept $7.19 billion and paid $7.23 billion in dividends. The next year it kept $7.67 billion and paid $7.64 billion. So far in 2026, through the first 36 weeks, it kept $5.77 billion and paid $5.94 billion.
PepsiCo set the 2026 dividend in February, a 4 percent raise. On October 8, when it cut its profit forecast, it kept it.
PepsiCo in Bufetico puts all three questions on one screen.
If I owned PepsiCo, I’d open its next annual report, which usually comes out in early February, and go to the cash flow statement. I’d take the cash from operations, subtract what it spent on plants and equipment, and put the dividends right next to what’s left. If the dividend keeps taking all of it, the buybacks and any company it buys have to be paid some other way, like new debt.
If you own PepsiCo or you’re about to buy it, the company makes a good profit and its sales grow. But it owes more than it did at the end of 2024, and its price is way above what it’s worth, going by how fast it’s growing. To me that’s expensive.
A dividend can make it easy to stop looking. You picked PepsiCo so you wouldn’t have to worry about it, and that one line in the cash flow statement is how you find out if you should.
Key factsThe numbers and where they come from · 23 October 2026
- In 2025, PepsiCo’s operations brought in $12.09 billion of cash and it spent $4.42 billion on plants and equipment, which left $7.67 billion. It paid $7.64 billion in dividends, bought back $1.0 billion of its own stock and spent $3.39 billion buying companies (annual report for 2025).
- PepsiCo’s dividends were bigger than the cash it kept after paying for plants and equipment in 2024 ($7.23 billion against $7.19 billion) and in the first 36 weeks of 2026 ($5.94 billion against $5.77 billion) (annual report for 2025, third-quarter results).
- On October 8, 2026, PepsiCo lowered its forecast for 2026 core constant currency earnings per share growth to 1 to 2 percent and kept its plan to return $8.9 billion to shareholders, $7.9 billion of it in dividends (third-quarter results).
- PepsiCo laid off 143 employees at its plant in Cheverly, Maryland, on September 14, 2026 (The Washington Post, October 18, 2026).