 Bufetico

You read a good margin and feel safe. The number doesn’t tell you that what’s under it may have changed completely. A federal deadline got Kathy Horan into her first new car in more than a decade. She’s lived for years in the North Bay, north of San Francisco. With the federal tax credit on electric cars about to end, she traded in her hybrid for a fully electric car. She told CBS San Francisco what she said the moment the cuts started: “Well, there is my timeframe.”
The credit took up to $7,500 off a new electric car. It was written into a 2022 law, and the tax bill signed in July 2025 ended it on September 30. California’s governor had already said the state wasn’t going to step in with a rebate of its own.
Plenty of buyers had the same idea. In the last days, Tesla’s website had a clock counting down to the order cutoff for the credit, NPR reported. Two days after the deadline, Tesla announced the most deliveries it had ever made in a quarter, and CNN said the jump came from Americans buying before the credit ran out. The same announcement had a second record in it, for the batteries Tesla sells to homes and power companies.
Two businesses in one number
In the year of the rush, Tesla’s gross margin came out almost exactly where it had been. Gross margin is what’s left of each sales dollar after paying the cost of making what was sold. Tesla’s annual report puts it at 18.0 percent in 2025, against 17.9 percent in 2024 and 18.2 percent in 2023. If all you had were those three numbers, and somebody asked whether that’s a good profit margin for a carmaker, you’d probably call it steady and move on.
Horan knew her deadline, and the law spelled out what the credit was worth. A company’s margin is harder to read. It’s an average of different businesses, plus some sales that cost almost nothing to produce. And an average can sit still while its parts move hard in opposite directions. At Tesla, they did.
Tesla reports two businesses. One sells and leases cars and runs the services around them, like charging, insurance and used cars. The other sells batteries for homes and power grids, plus solar. The car margin covers cars sold and leased, plus the regulatory credits Tesla sells to other carmakers, which no car buyer pays for. It fell every year, from 19.4 percent in 2023 to 17.8 in 2025. The energy margin went the other way, from 18.9 to 29.8, while energy sales more than doubled. So the part earning more on each dollar was also getting bigger, and the average held.
Some of that energy margin came from the same law behind the credit Horan was chasing. That law also gives manufacturers a tax credit for the batteries they make. Tesla counts that credit as a cut in its costs, so it lifts the margin without ever showing up as sales. In the energy business, the credit came to $115 million in 2023 and $1.12 billion in 2025. Take it out, and the energy margin goes from 17.0 percent to 21.0 over those two years. So of the 10.9 points the energy margin gained, four came from the business getting better, and the other 6.9 came from the credit.
When a company reports more than one business, I split its margin by business before I judge it, because a steady total can hide two trends going opposite ways. And when part of the margin doesn’t come from the product itself, like credits counted as lower costs, or sales with no cost of their own, I read the margin with them and without them. Tesla’s car margin has one of those, the regulatory credits. With the credits out of both sales and profit, the cars earned 15.4 percent in 2024 and 15.4 in 2025. So the reported car margin came down because the credits brought in less than in 2024, and that’s the main reason Tesla gives.
Where this breaks
The split between cars and energy depends on how Tesla divides the costs the two share, like factories and overhead. Split those costs another way, and both margins move. I use the split Tesla reports because it’s the only one on the record.
I can also only take out what a company tells me about. Tesla gives the size of its manufacturing credit in a note to its accounts, the fine print at the back of the report, away from the income statement itself. When a company doesn’t, the credit stays buried in its costs, and the whole margin looks like it came from the business. And the government’s help keeps changing. Tesla’s annual report says the July 2025 law cut back much of the 2022 package, though some of it survives under tighter rules.
The deadline Kathy Horan raced
Horan had the keys to her new car on Thursday, September 25, 2025, five days before the deadline. The help she raced for came from the federal government, with an end date she could see. Tesla’s car margin had some help too, from those regulatory credits. Governments in several places set rules on how clean a carmaker’s cars have to be, across everything it sells. A carmaker that falls short can pay one that beats the rule for its spare credits. Tesla’s annual report says it sells those credits to other carmakers as its new cars are sold, and that they cost it almost nothing extra. And the report says the same law that ended the EV tax credit did away with some of the penalties for breaking those rules.
The regulatory credits brought in $1,993 million in 2025, a little more than the $1,790 million in 2023. But Tesla’s profit shrank. Its operating income is the profit left after the costs of running the company, like research and administration. It fell from $8,891 million to $4,355 million over those two years, as those costs grew. So close to half of the $4,355 million came from other carmakers.
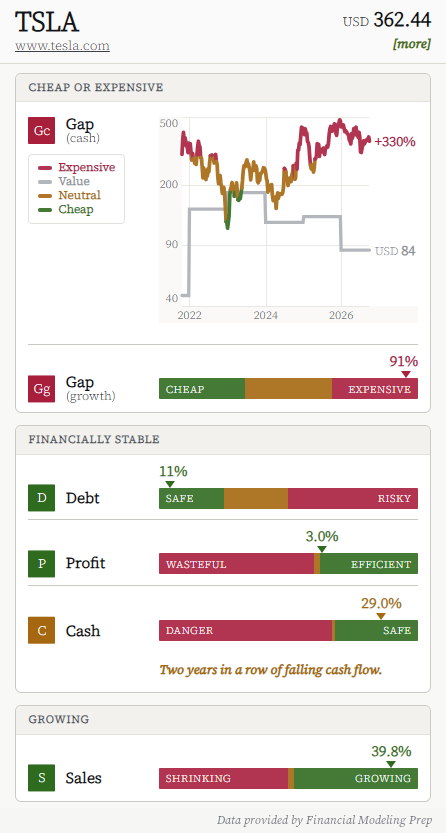
This is Tesla in Bufetico. On one screen I see if Tesla is cheap or expensive, if it’s financially stable and if it’s growing.
If I owned Tesla, I’d pull up its annual report and figure out the car margin and the energy margin. Then I’d take the regulatory credits out of the car numbers and the manufacturing tax credit out of the energy numbers, and see what each business earns by itself.
If you own Tesla or you’re about to buy it, the company doesn’t owe much and it’s growing, but the cash it brings in has fallen two years in a row. Its price also sits way above what Tesla is worth, going by the cash it brings in each year, and to me that’s expensive.
A steady margin will still make you feel safe. Tesla’s gross margin barely moved while its car margin fell every year.
Key factsThe numbers and where they come from · 18 September 2026
- Tesla’s gross margin was 18.0 percent in 2025, against 17.9 percent in 2024 and 18.2 percent in 2023, according to its annual report.
- Tesla reports two businesses, and from 2023 to 2025 its car margin fell from 19.4 percent to 17.8, while its energy margin rose from 18.9 to 29.8 and energy sales more than doubled.
- Tesla counts a manufacturing tax credit for batteries as a cut in its costs. In its energy business, that credit came to $115 million in 2023 and $1.12 billion in 2025, the annual report shows.
- Regulatory credits sold to other carmakers brought Tesla $1,993 million in 2025. Its operating income fell from $8,891 million in 2023 to $4,355 million in 2025, the annual report says.