 Bufetico

Every earnings call has a buyback in it somewhere, and you’re not sure what it does for you as an owner. John Ternus joined Apple as an engineer on the design team. “I wasn’t sure I belonged there,” he has said of his first day. In 2024 he told engineering graduates at Penn that the people he met knew so much more than he did. He said he’s grateful he wasn’t afraid to ask for help. Twenty-five years after that first day, on September 1, 2026, he took over from Tim Cook as Apple’s chief executive.
Eight days later he borrowed Steve Jobs’s old one-more-thing line and unveiled an iPhone that folds like a book. NPR said the iPhone’s shape hadn’t changed this much since the first one. Products are his home turf. He’s spent most of his career on the side of Apple that makes things. In a 2023 interview with CNBC, he talked about the technology: chips, battery life and memory.
The part of the job with no keynote
But the CEO’s job covers a lot more than products. As CNBC noted the morning he started, it runs all the way to finance and legal. And the finance part never gets a stage. It’s the question of what Apple does with all the cash its products bring in.
He talked about that part on Apple’s earnings call in April, ten days after Apple named him. He told investors that he and the finance chief, Kevan Parekh, plan to keep the discipline Cook brought to decisions about money. On the same call, Parekh laid out the order Apple spends its cash in. The business gets every investment it needs, and whatever cash is left after that goes back to shareholders over time.
So that’s why a company buys back its own stock. Once the business has what it needs, there’s still cash left over, and there are two ways to hand it back. The company can pay a dividend, which is cash sent to every shareholder. Or it can buy its own shares in the market and cancel them. Apple does both, and most of the money goes into buying shares.
What the money bought
The company Ternus took over has been canceling its own shares for years. A canceled share stops existing, so every share that’s left is a bigger piece of the company. Apple spent $577,838 million doing that in the seven fiscal years through 2025, by my sum of its annual reports. That’s more than half a trillion dollars. Over those seven years, the share count fell about 22 percent, so a bit more than one share in five is gone. Since September 2021, it’s down about 11 percent. Ternus joined the executive team that year.
The count falls more slowly than all that cash would suggest. That’s because Apple pays its people partly in stock, and those are new shares. So some of the buying just cancels them out.
Fewer shares also move the numbers people quote. In fiscal 2023, with Ternus running hardware engineering, Apple’s profit fell, but its profit per share still went up, from $6.11 to $6.13. The profit was split over fewer shares. So when profit per share grows, I check the share count before I give the business the credit.
The nine weeks Apple bought nothing
When a dividend goes up every year, it turns into a promise, and cutting it reads as bad news. A buyback is different. The company can turn it up or down whenever it wants, and Apple’s filings say its programs don’t oblige it to buy any minimum number of shares.
From March 1 to May 2, nine weeks that included the day it named Ternus, Apple didn’t buy back any of its own shares. In the same weeks a year earlier, it had been buying. On the April call, Parekh said buyback activity can be affected by a number of things, and in the same breath he mentioned the CEO transition.
What Apple paid
When Apple started buying again in May, with Ternus already named, it paid an average of $297.18 a share on the open market. In a buyback, Apple pays whatever the market asks that day, like any other buyer. So the higher the price, the fewer shares each dollar takes off the count.
And the cash has to come from somewhere. In the seven years I added up, the cash Apple’s business brought in, after paying for its buildings and equipment, came up short of what it handed back in buybacks and dividends.
Where this breaks
The cash Apple pays shows up in the cash flow statement, and the shares it cancels show up in the share count. In any given year, the two don’t line up exactly. Trades made near the end of a period get paid in the next one. And some of the buying runs through contracts where Apple pays a bank up front and gets the shares over the following months, like the ones it signed in May. There’s also a one-time tax inside those seven years. In fiscal 2025 Apple paid Ireland back taxes out of an escrow, money it had set aside years before in a separate account. That payment comes out of what the business brought in. Put it back, and the business still falls short. And fiscal 2023 had 53 weeks instead of the usual 52, which flatters the comparison with 2022 a little.
Buybacks also take money off the balance sheet. That’s part of why Apple’s equity, what its books say belongs to the owners, looks small next to everything it owns. And it’s why I don’t lean on a debt ratio built on equity at a company like this. I wrote about that at McDonald’s. If the company overpays, the owners who stay get an extra slice that’s worth less than the cash that went out to buy it. And none of this says the shares were worth what Apple paid for them. Apple doesn’t publish what it thinks they’re worth.
The savings Ternus inherited
The part the business didn’t cover came out of savings, and Apple did that on purpose. Since 2018, Apple had a goal it called net cash neutral. The idea was to bring its net cash down to about zero. Net cash is the cash and investments it holds, minus what it has borrowed. By its finance chief’s count, net cash has come down by more than $100 billion since then.
But it had already started coming back. By my arithmetic from Apple’s filings, net cash was $33,763 million in September 2025 and $62,173 million at the end of June, two months before Ternus’s first day as CEO. That’s almost double.
On that same April call, with Ternus on the line, Parekh said net cash neutral was no longer a target.
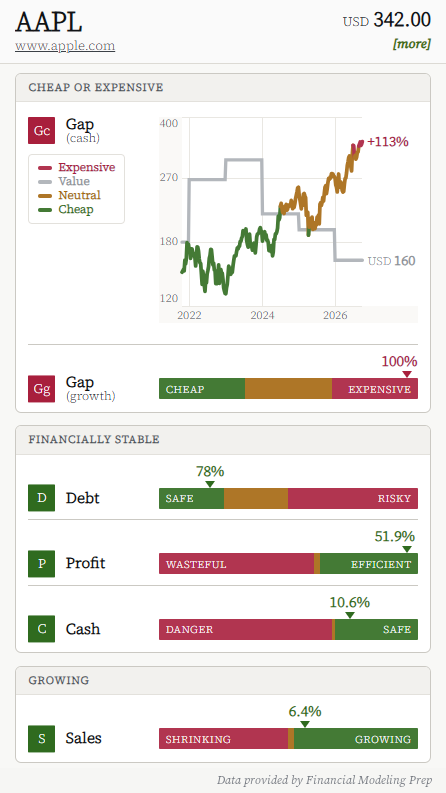
Apple looks like this in Bufetico.
If I owned Apple, I’d go straight to its cash flow statement and take what the business brought in, minus what it paid for buildings and equipment. I’d put that next to the buybacks and the dividends. Then I’d check net cash, to see how much of what the business didn’t cover came out of savings.
If you own Apple or you’re about to buy it, the company is financially stable and it’s growing. But its price sits way above what Apple is worth, going by the cash it brings in every year, and to me that’s expensive.
Every earnings call is still going to mention a buyback. Check the share count before you nod along.
Key factsThe numbers and where they come from · 22 September 2026
- Apple’s annual reports, added up, show $577,838 million spent buying its own shares in the seven fiscal years through 2025. Its share count fell about 22 percent in that time.
- From March 1 to May 2, 2026, Apple bought none of its own shares. When it started again in May, it paid an average of $297.18 a share on the open market (Apple’s quarterly report).
- Over those seven years, the cash Apple’s business brought in after paying for buildings and equipment fell short of what it handed back in buybacks and dividends, according to its annual reports.
- Since 2018 Apple had aimed for net cash neutral, bringing cash and investments minus borrowing down to about zero (CNBC). On its April 2026 earnings call, finance chief Kevan Parekh said that was no longer a target.