 Bufetico

You know the coffee. You drink it every morning, and maybe you own the stock too, without ever looking at what the company owes. Baylor Baucom has been a Starbucks barista for five years. On a Saturday morning in August 2026, baristas shut a Starbucks in Goodlettsville, just north of Nashville, for the day. A crowd of workers and neighbors chanted that no contract meant no coffee, and cars kept pulling into the drive-through anyway. Some honked. Some stopped to ask what was going on. The Nashville Banner was there and talked to Baucom.
What the baristas told the paper was pretty simple. Staffing has gone down year after year, but the work expected from the people who are left hasn’t. Some shifts run with just two people on the floor. Baucom talked about everything those two have to cover: the drinks, the food, the orders at the counter and the orders at the window. He said it gets to your mental health. You’re short-staffed, you’re told to go faster, and then you turn around and a customer is yelling because the wait was too long. “We’re serious, and we need help,” he said.
Rachael Cullen, who works at the Goodlettsville store and has been a barista for two years, was angry about something else. In May, Starbucks and the state announced a corporate office in Nashville with 2,000 jobs, and Tennessee put in a $30 million grant to help it along. The Banner says a barista in 43 states starts at $15.25 to $16 an hour. Starbucks told the Banner it’s still bargaining in good faith, and that pay and benefits for eligible hourly workers average more than $30 an hour.
Nearly every store Starbucks runs is rented. Its annual report for fiscal 2025 counts 21,514 stores the company runs itself, almost all of them leased, so the one the baristas closed that Saturday almost certainly is too. That’s where the balance sheet comes in. The two lines on it that people quote the most are about those stores and about the shareholders, and they get mixed up all the time.
One balance sheet, two lines that get mixed up
At the end of June, Starbucks had shareholders’ equity of minus $7,674 million. That’s what the books say belongs to the owners, and it’s below zero. A few lines up on the same balance sheet, under what the company owes, there’s $7,884 million of long-term lease obligations. It’s mostly rent the company has promised to pay on stores like the one in Goodlettsville.
The two numbers are almost the same size, and they point opposite ways. I’ve seen both used as proof of the same thing, that the company is in trouble. But they have nothing to do with each other. One is there because the company decided to do something. The other is there because an accounting rule changed.
The decision
Starbucks’ equity went below zero at the end of 2018 and has stayed there since. The reason is sitting right on the cash flow statement. The company spent $7,133 million buying back its own shares in fiscal 2018, and $10,222 million in fiscal 2019. Equity works like a running total: everything ever put into the company, minus everything ever taken out. Take out that much for long enough and the total goes below zero. That’s all negative equity is. Starbucks has handed back more than was ever put in, from a business that kept earning.
On its own, that’s just history. Reading it as a sign of trouble is the mistake I wrote about with Etsy on September 8, 2026. And the habit didn’t end with the big years. In fiscal 2025, profit came in at $1,856 million, down from $3,761 million the year before, and Starbucks still paid $2,771 million in dividends. That’s more than it earned. It bought back no shares that year, after $1,267 million the year before. I don’t know what that pause means. The filing only shows that it happened the same year profit halved.
The rule
Now look at the lease line year by year. In fiscal 2019 there’s no such line. In fiscal 2020 it’s $7,662 million. The stores didn’t appear overnight. Starting in fiscal 2020, the accounting rules made companies put their lease commitments on the balance sheet. Before that, the leases lived in a note at the back of the report, in words and a table. Starbucks owed the same rent to the same landlords the day before the rule and the day after. What changed is that you could see it without turning to the notes.
I keep coming back to this one because of what it means for every year before the rule. If a balance sheet ratio told you a coffee chain was comfortable in 2018, that ratio was leaving out a fixed commitment about the size of the company’s debt.
What the two lines say about a Saturday in Goodlettsville
Put the two lines side by side and you can’t say the company is in trouble, and you can’t say it’s fine either. Starbucks has handed huge amounts of money back to shareholders, and that’s why the equity line is negative. It also carries close to $7.9 billion of rent it can’t get out of. That’s what it costs to have stores right where people drive by. The two numbers got there for different reasons. But both of them decide what’s left for shareholders once the landlords are paid. And neither one tells you how the last six months went.
Now think about that shift with two people on the floor. The rent on that store is set by a contract, and the annual report says the company’s leases have 8.6 years left on them, on average. The hours are set by whoever writes the schedule. A Saturday with two baristas costs the same rent as a Saturday with three. Of everything it takes to keep that store open, the hours can be cut, and the rent can’t. Any other chain works the same way.
So the equity line tells you what already happened, and the lease line tells you what’s owed. I look at whether the cash the business makes covers what it’s promised, and how much is left over after that.
Where this breaks
The risk with all this is that it sounds reassuring. I’ve spent this article saying negative equity isn’t a sign of trouble and the lease line isn’t new debt. Both are true. But that doesn’t make either number harmless. Starbucks owes that rent. It comes due on a date, to a landlord, and unlike a dividend, the company can’t skip it in a bad year. A company with a big fixed bill and a shrinking profit has less room than one without. Getting the accounting right doesn’t change that.
There’s a trap in that June number too. In that same quarter, Starbucks sold 60 percent of its China business to Boyu Capital and stopped counting it as its own. So the June lease line leaves those stores out, and that’s most of why it’s $7,884 million, lower than the $8,972 million of September 2025. The June equity line also includes a $536.3 million gain on the sale, before taxes. That means the two dates aren’t counting the same stores.
The line that store is on
The rent itself shows up in the lease note at the back of the annual report, in a small table of supplemental information. The line is called cash paid related to operating lease liabilities. It was $1,901.4 million in fiscal 2025, up from $1,672.5 million the year before. That’s the fixed rent Starbucks paid to the landlords of stores like the one in Goodlettsville. Further down the same note is what falls due in fiscal 2026: $1,940.6 million.
In Bufetico, Starbucks gets the same three questions as any company I look at: cheap or expensive, financially stable, and growing.
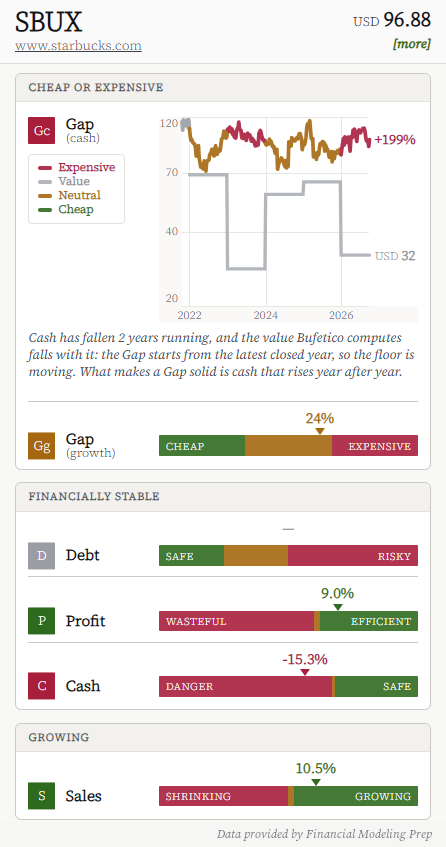
If I had Starbucks in my portfolio, I’d skip the equity line and go to the lease note at the back of the annual report. I’d put the rent coming due next to the cash the business brings in, and see how much is left for the dividend once the landlords are paid. And I’d make sure the two balance sheets I compare cover the same stores.
If you own Starbucks or you’re about to buy it, its sales are growing, but the cash the business brings in has been going down. Its price also sits way above what Starbucks is worth, going by the cash it brings in each year, and to me that’s expensive.
You’ll still drink the coffee every morning. If you own the stock too, the rent on the stores Starbucks runs is a bill it can’t skip in a bad year.
Key factsThe numbers and where they come from · 11 September 2026
- At the end of June 2026, Starbucks had shareholders’ equity of minus $7,674 million and $7,884 million of long-term lease obligations, most of it rent on its stores (Starbucks’ quarterly report).
- Starbucks’ equity went below zero at the end of 2018 and has stayed there since. Its cash flow statements show $7,133 million of buybacks in fiscal 2018 and $10,222 million in fiscal 2019.
- In fiscal 2025, Starbucks earned $1,856 million, down from $3,761 million the year before, and paid $2,771 million in dividends without buying back any shares (Starbucks’ annual report).
- Cash paid on Starbucks’ operating leases was $1,901.4 million in fiscal 2025, up from $1,672.5 million the year before, and $1,940.6 million falls due in fiscal 2026, according to the lease note in the same report.